Showing posts with label subprime. Show all posts

Sunday, November 18, 2007

Poof!

David Seaton's News Links
There is a wonderful saying in Spanish, "eramos pocos y parió la abuela", which translates literally as, "there were only a few of us and grandmother gave birth" and means, "it was the last straw". Obviously the English version gives none of the surreal exasperation of the Spanish original.

This saying comes to my mind constantly when I put the economic news alongside the geopolitical stuff. So many calamities taken all together become a thing to itself, the quantity turns into a quality, something called a "tipping point".

Tipping into what? That is the question. DS


Nouriel Roubini says:

I now see the risk of a severe and worsening liquidity and credit crunch leading to a generalized meltdown of the financial system of a severity and magnitude like we have never observed before. In this extreme scenario whose likelihood is increasing we could see a generalized run on some banks; and runs on a couple of weaker (non-bank) broker dealers that may go bankrupt with severe and systemic ripple effects on a mass of highly leveraged derivative instruments that will lead to a seizure of the derivatives markets (think of LTCM to the power of three); a collapse of the ABCP market and a disorderly collapse of the SIVs and conduits; massive losses on money market funds with a run on both those sponsored by banks and those not sponsored by banks (with the latter at even more severe risk as the recent effective bailout of the formers’ losses by theirs sponsoring banks is not available to those not being backed by banks); ever growing defaults and losses ($500 billion plus) in subprime, near prime and prime mortgages with severe known-on effect on the RMBS and CDOs market; massive losses in consumer credit (auto loans, credit cards); severe problems and losses in commercial real estate and related CMBS; the drying up of liquidity and credit in a variety of asset backed securities putting the entire model of securitization at risk; runs on hedge funds and other financial institutions that do not have access to the Fed’s lender of last resort support; a sharp increase in corporate defaults and credit spreads; and a massive process of re-intermediation into the banking system of activities that were until now altogether securitized. READ IT ALL

Wednesday, November 07, 2007

Born under a bad sign

Born under a bad sign.
Ive been down since I began to crawl.
If it wasnt for bad luck,
I wouldnt have no luck.
If it wasnt for real bad luck,
I wouldnt have no luck at all.
Booker T. Jones and William Bell
David Seaton's News Links
In the same week that oil pushed toward a hundred dollars a barrel, the financial News agency Bloomberg reported that, “The dollar fell to a record low against the euro on speculation financial-company losses from U.S. subprime-mortgage defaults will grow.” New York University economics professor, the always clairvoyant Nouriel Roubini, added, “the ongoing credit crunch will get much worse in the year ahead and its fallout spread from the US to Europe and throughout Asia and the globe. (...) The first crisis of financial globalization and securitization is thus only at its beginning stage.” At precisely this moment Pakistan took another step toward the abyss.

The veteran analyst Arnaud de Borchgrave wrote, “One of the world’s eight nuclear powers, Pakistan is now a failing state out of control where Taliban, al-Qaida and their supporters have secured their privileged sanctuaries in the tribal areas on the Afghan border; reoccupied the Red Mosque in the center of Islamabad; launched suicide bombers in widely scattered parts of this Muslim country of 160 million. More than any other country in the world, Pakistan is the breeding ground of Islamic terrorism.” The New York Times editorialized, “The United States is increasingly left with bad options. Cutting off aid would only make it harder to enlist Pakistan’s military in the anti-extremist fight and renew doubts about America’s reliability as an ally.” The Guardian’s editorial stated it even more baldly, “Gen Musharraf has called Washington and London's bluff, knowing they have no option but to back him. The general has exposed the impotence of the US and Britain to control a key ally with nuclear weapons.” The Pakistani army is the true center of power: all that holds a geographically and ethnically divided Pakistan together and the generals are not about to give up that role. If Musharraf falls, another general will be there to take his place... perhaps one who attends more to his prayers.

A sailor would touch wood and call this the approach of the perfect storm, an astrologer looking at the ephemeris would speak of an inauspicious aligning of the planets, a master of Diamat could speak of contradiction, of quantity becoming quality and a Hindu might simply smile and speak of the "Dance of Shiva". The fact is that the bad news is beginning to accumulate in a most alarming way: catastrophe: war, terrorism, inflation and now the possible collapse of major banks. Any one of these things would itself be a painful blow, taken together they begin to define our time. DS

Wednesday, October 17, 2007

How many divisions (investment funds) has the Dalai Lama got?

David Seaton's News Links
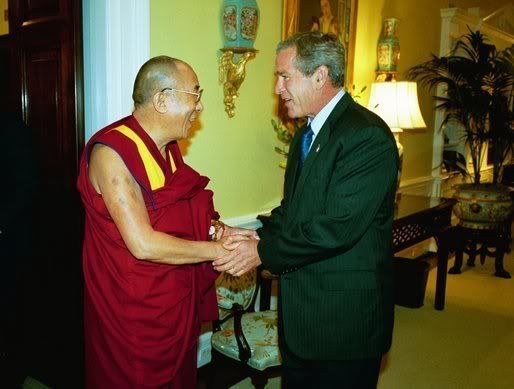
The Dalai Lama is a great spiritual leader, I follow his discourses with great interest, indeed reverence. However, as a chief of state, I can't see that he is a great example of the democratic principals that George W. Bush says he is committed to bringing to the world with fire and the sword.

As I understand it Tibet's chief of state is chosen when a group of monks show a child personal effects of the last chief of state and if he recognizes them as his own, then he becomes the new chief of state... Come to think of it, that's not a whole lot different to the way Bush got to chief of state himself. Still I don't see why it was absolutely necessary to offend China on democratic principals. Because China is in a position to express its displeasure in many interesting ways.

People who understand money tell me that there is a liquidity crisis in the world, a rather desperate shortage of cash.

China has a huge amount of cash. They want to invest it in the west. It seems to me that this information doesn't square with the photo above.

In the same way I don't understand the timing of the Armenian genocide vote in the US Senate, I don't understand the timing of the photo above. Somebody is going to end up being humiliated and I don't think it's going to be the Chinese. DS


Martin Wolf: The brave new world of state capitalism - Financial Times
Abstract: Globalisation was supposed to mean the worldwide triumph of the market economy. Yet some of the most influential players are turning out to be states, not private actors. States play a dominant role in ownership and production of raw materials, notably oil and gas. Now states are also emerging as owners of wealth. This is creating widespread concern. Does that narrow focus make sense? The broad answer is No.(...) In all, they control some $2,200bn, with $2,100bn in the top 20 funds. The seven biggest belong (in order of estimated size) to Abu Dhabi ($625bn), Norway ($322bn), Singapore – GIC ($215bn), Kuwait ($213bn), China ($200bn), Russia ($128bn) and Singapore – Temasek ($108bn).(...) The sovereign funds remain far smaller than official foreign currency reserves (approximately $5,600bn). But the expectation is that these funds will grow rapidly, possibly to exceed official currency reserves in a number of years. If recent growth were to continue, the total value would reach $13,000bn over the next decade. This might then be 5 per cent of total global financial wealth.(...) Many sovereign wealth funds should raise no concerns whatsoever. The worrying ones are only those that do seek dominant positions or outright ownership of strategically important businesses. If the fund belonged to a government deemed potentially hostile, the concern must be bigger. It would be reasonable to keep control of companies operating in defence or high technology out of the ownership of funds belonging to any foreign government, let alone a potentially hostile one. But interesting questions arise elsewhere: what would people feel about Chinese government ownership of a big media operator?(...) the owners of the sovereign wealth funds need to understand their own best interests. They should manage their money professionally and transparently. This is also the way to minimise friction with host countries. If they refuse to abide by these principles, they must expect trouble. Yet trouble should not go out of its way to look for them: far, far worse things can happen than for China to come to the west bearing the chequebook it has earned by its people’s remarkable efforts. READ IT ALL

Wednesday, March 28, 2007

Bloomberg's garden of verses

"Without much thought, you'd say people wouldn't want to lose their home so they'd first make the house payment,'' Risi said. ``But with a lot of the borrowers struggling to make their house payments, to get any cash, they have to get to work. And that's what they need their car for.''
David Seaton's News Links
Here, in Bloomberg's cold facts and figures is a little poem of suffering. DS


Subprime Defaults May Spread to Auto Bonds, S&P Says - Bloomberg Abstract: Bonds backed by automobile loans may be hurt by rising subprime mortgage defaults as people with poor credit struggle with their household debt, according to Standard & Poor's. Capital One Financial Corp., Wachovia Corp., Wells Fargo & Co., and other lenders have lent more funds to people with bad credit scores in the past few years to sustain growth, S&P said today in a report by analysts led by Mark Risi. The loans are also for longer terms, increasing the probability of default, the analysts said. About 68 percent of 2006 subprime auto loans were due in five years or more, Risi said. ``There could be some fallout from subprime in auto loans,'' Risi said in an interview. ``We don't have much data yet. We're still in collection mode. It's probably going to be hard to say for a while.'' The worst housing slump in 10 years is pushing down home prices, hampering owners from refinancing. Borrowers with weak or incomplete credit are also vulnerable to the resetting of mortgages at more than the teaser rates they initially paid.(...) Subprime auto borrowers who are also homeowners may have ``exposure to affordability products and the related payment shock,'' said Risi. ``But the good news is, initial data indicates that the majority of subprime auto borrowers are renters, and are therefore not subject to the vagaries of the mortgage market.'' Subprime auto bonds are showing a wide disparity in performance depending on the issuer, the analyst said. With some subprime issuers moving further down the credit spectrum and some resisting that trend, ``we are seeing some interesting results from this divergence,'' Risi said. Bondholders cannot tell which subprime auto borrowers are also homeowners, Risi said. Cumulative losses over 10 months for DaimlerChrysler AG's most recent loans is at 0.58 percent, its highest since at least 2000, S&P said. Securities originated by General Motors Acceptance Corp., that automaker's former finance arm, are showing losses of 0.18 percent, the lowest rate since 0.15 percent in 2002, according to S&P. Ford Motor Credit Co.'s loss rate is 0.25 percent, the same as in 2005. Given a choice between making a car payment or paying the mortgage, consumers react in different ways, Risi said. ``Without much thought, you'd say people wouldn't want to lose their home so they'd first make the house payment,'' Risi said. ``But with a lot of the borrowers struggling to make their house payments, to get any cash, they have to get to work. And that's what they need their car for.'' READ IT ALL

Saturday, March 17, 2007

The brink of bad times

"You can't believe how bad it's going to get before it gets any better."
Jim Rogers - commodities investment guru
David Seaton's News Links
My perspective is political, so I look at the coming disaster with that slant. I have the good fortune to know quite a few top Spanish financial folk who have been explaining all the details of the economic situation to me patiently... over and over for years, and although I really can't claim to understand any of this stuff, from my slant I have grabbed on to one or two "hinges" upon which the situation seems to turn... Again, from my particular, political, point of view.

In the article I've clipped below, Jim Rodgers, George Soros old partner says, "This is the end of the liquidity party". He also says, "We haven't had this kind of speculative buying in U.S. history." What does this mean politically?

The world has been swimming in money (liquidity) for years now and many "middle-middle-class" people (defined as people who live from their work and whose principal asset is their family home) have been living way beyond their means and have come to acquire the social attitudes of upper middle class people, (defined as those whose patrimony is deep and layered, with mature stock portfolios, multiple inheritances, land and the "taken with mother's milk" habit of managing all those things). Under this delusion these middle-middle-class" folk, once the "salt of the earth", have come to think of themselves as "players" and have identified with characters such as Bill Gates and Warren Buffet or even Donald (ugh!) Trump, as aspirational, fantasy figures.

So, not only is there going to be a lot actual hardship, but also terrible disillusionment... the end of a dream. Because to add insult to injury, the victims in this crash are going to have salt poured into their wounded self esteem, because the system is going to treat them with all the same compassion with which it treated the stranded black people of New Orleans.

There is this idea, taken from our Christian heritage, that suffering makes people better, even holy. It would be comforting to think that this economic wasteland of broken dreams would wake the victims up and make them more compassionate and raise their consciousness... (hum a few bars of "The International" here if you wish). That like in the days of the Great Depression there would be a surge of brotherhood, (Liberty, equality, fraternity?). Unfortunately suffering can also turn quite a few people into mean spirited sons of bitches. Mean spirited sons of bitches when organized are often called "fascists".

This coming crisis is the great, "to be or not to be", challenge for progressive politics. DS

Top investor sees U.S. property crash - Reuters

Abstract: Commodities investment guru Jim Rogers stepped into the U.S. subprime fray on Wednesday, predicting a real estate crash that would trigger defaults and spread contagion to emerging markets. "You can't believe how bad it's going to get before it gets any better," the prominent U.S. fund manager told Reuters by telephone from New York. "It's going to be a disaster for many people who don't have a clue about what happens when a real estate bubble pops. "It is going to be a huge mess," said Rogers, who has put his $15 million belle epoque mansion on Manhattan's Upper West Side on the market and is planning to move to Asia. Worries about losses in the U.S. mortgage market have sent stock prices falling in Asia and Europe, with shares in financial services companies falling the most. Some investors fear the problems of lenders who make subprime loans to people with weak credit histories are spreading to mainstream financial firms and will worsen the U.S. housing slowdown. "Real estate prices will go down 40-50 percent in bubble areas. There will be massive defaults. This time it'll be worse because we haven't had this kind of speculative buying in U.S. history," Rogers said. "When markets turn from bubble to reality, a lot of people get burned." The fund manager, who co-founded the Quantum Fund with billionaire investor George Soros in the 1970s and has focused on commodities since 1998, said the crisis would spread to emerging markets which he said now faced a prolonged bear run. "When you have a financial crisis, it reverberates in other financial markets, especially in those with speculative excess," he said. "Right now, there is huge speculative excess in emerging markets around the world. There will be a lot of money coming out of emerging markets.(...) The last stock market bubble to burst was the dot-com craze which sparked a crash from March 2000 to October 2002. When the last bubble burst in Japan, said Rogers, stock prices went down 85 percent despite the country's high savings rate and huge balance of payment surplus. "This is the end of the liquidity party," said Rogers. "Some emerging markets will go down 80 percent, some will go down 50 percent. Some will most probably collapse." READ IT ALL

Friday, March 16, 2007

Subprime crisis: from sushi to meatloaf

"The sub-prime carnage is now front page news on every possible media; soon enough it may be even become cover story on People magazine as even Britney Spears will soon be asking about it." Nouriel Roubini

David Seaton's News Links
If you are too young to to have clear memories of the cold war it will be impossible for you to imagine how all embracing it was. Bush and Cheney have been trying to "recreate" the cold war's tension in their "Great War On Terrorism" (GWOT), but they don't even come close. It went from horizon to horizon. Like living in the same room with a dangerous animal... for both sides.

So, when the Soviet Union went down there was a huge sigh of relief. Instead of thinking that if such a huge and powerful system could collapse, any system could collapse, that collapse was in the nature of huge and powerful systems, there was a sense of "victory" accompanied by euphoria.

To give you an idea of the period, in 1992, sober and reputable Francis Fukuyama published, "The End of History and the Last Man", where he wrote, "What we may be witnessing is not just the end of the Cold War, or the passing of a particular period of post-war history, but the end of history as such: that is, the end point of mankind's ideological evolution and the universalization of Western liberal democracy as the final form of human government." In real life people only say things like that when they sniff cocaine.

Meanwhile in the United States, during the 80's, while the Soviet Union was preparing to collapse, amazing things were happening in the world of finance. The definitions of money and value were revolutionized. The symbol of this revolution was the "Junk Bond" and its Lenin was Michael Milken. A new way of looking at money and the ways to use it was born.
The film that symbolized this revolution was Oliver Stone's, "Wall Street".

Simultaneously, the power of computers began its geometric increase that has become so familiar to us over twenty years later. This increase in computer power made it possible to calculate financial risk in a much more sophisticated way. So everything was in place: euphoria and new ways of creating value seemingly out of thin air.

The result was that huge amounts of money appeared in the newly deregulated world and began to move at a dizzying speed. It became easier and easier to borrow money, in increasing quantities, at lower rates and for longer times. People who had heretofore worked hard to make ends meet, to own their own home and to send their kids to school, began to feel "rich". In fact the only thing they really owned was the house they lived in, whose theoretical value was increasing daily and against whose "paper" value they contracted real debts. It looks as if the party may be over and as in the "Crash of 29" creditors may panic and call in their loans... with devastating and unpredictable knock on effects.

Politically this will mean that a lot of people, with a good education and brilliant prospects, who thought they were rich will suddenly feel that they are poor, they will make a lightning fast voyage from sushi to meatloaf.
Normally people take too much credit for their successes and often blame themselves too much for their failures. It takes a very wise man or woman to look in the mirror and to see a fool and then to shrug this vision off.

Many will feel betrayed by the very system they thought they understood and knew how to game. This declassing and sudden insecurity is often the origin of much bitterness and political agitation... normally it offers opportunities for the far-right. The left must be prepared to offer solid analysis and strong support, both moral and material to the victims of what appears to be a severe fall to earth for the "nouveau pauvre"... or risk being swept away by their rage. DS


Leap of faith? How a fiasco of easy home loans has tripped up America - Financial Times

Abstract: Victoria Wagner, credit analyst at Standard & Poor's, the ratings agency, says some subprime mortgage lenders dramatically lowered their standards amid "the so-called democratisation of credit", granting loans that contained many levels of default risk. These included a lack of income documentation and no downpayment. Ms Wagner calls this kind of risky lending "unprecedented". Now buyers (...) are falling behind or defaulting, as interest rates that started relatively low go higher and home prices in some parts of the US stop rising. So far the problem has remained largely contained within the subprime sector. It may stay there but concern is growing that difficulties could spread throughout the housing market and then, perhaps, the wider US economy. The first way the subprime decline could impact on the housing market is if a flood of foreclosed homes came up for sale and pushed down prices in areas where the supply of homes is already high because demand has dropped off. "The big question is, how quickly will housing prices adjust lower as delinquency rates rise?" says Richard Gilhooly, senior fixed income strategist at BNP Paribas. Analysts at Lehman Brothers project that mortgage defaults could reach $225bn during 2007 and 2008 and perhaps go as high as $300bn. "The risk that they impact the broad housing market and begin to weigh upon prime borrowers is very real," they say. (...) Delinquency rates for subprime adjustable-rate mortgages, the riskiest kind, hit 14.4 per cent. The numbers could get much worse because many who bought homes face "resets" in their mortgage payments; the low rates that tempted them in will revert to higher, market-determined rates. Lehman estimates that more than $900bn of mortgages will hit a reset in the next two years.(...) Still, it is far from certain that the subprime ailments will infect the broader housing market. Steven Wieting, economist at Citigroup, suggests that the problems are likely to affect financial institutions and their investors - as indeed they already have - more than consumer sentiment and the economy at large. But if the marginal buyer - someone able to buy a house only if conditions are right - is knocked back, that could at best slow a recovery in the housing market. At worst, it could lead to recession. David Rosenberg, North American economist at Merrill Lynch and a perennial bear, says: "This housing downturn is far from over and the full impact across the economy has notbeen felt . . . As with most bubbles, this one started with loosening credit guidelines, excessive price appreciation, classic performance-chasing [and] speculative fervour, and nowends in lawsuits." Whatever the impact of the subprime fiasco on the wider economy, it is already deeply painful for many Americans.(...) One way the subprime shake-out could lead to systemic problems across the capital markets is if investors who had little idea they might own such mortgages suddenly discovered that they did. These holdings would probably be through complex structures called collateralised debt obligations - packages of asset-backed bonds. Investors in CDOs - say, pension funds in Europe or Japan - may be inclined to act more quickly when they detect subprime exposure than would a group that was already well aware of the risks in their CDOs. One problem is a lack of information. CDOs are rarely traded and difficult to value. As a result, buyers are often reliant on credit ratings to know when to sell. However, credit ratings regularly lag market prices, meaning that losses can be greater than necessary when the credit rating downgrade finally comes. Josh Rosner, managing director at Graham Fisher & Co, an investment research firm, says: "Because many buyers of CDOs can only hold investment-grade assets, they may continue to hold deteriorating and increasingly illiquid assets as long as credit ratings have not been downgraded." This means that when these investors eventually sell, they may also be forced to accept large losses in a fast-moving market. The heavier the losses, the less likely investors are to want to return, a classic case of "risk aversion". Such risk aversion is already clear among the commercial and investment banks that had provided funding to subprime mortgage lenders. Those banks cut off credit lines to New Century Financial and Accredited Home Lenders, pushing both close to bankruptcy filings. With equity investors in subprime (and even prime) mortgage lenders offloading their shares - "then asking questions later", according to David Hendler, an analyst at CreditSights - some industry executives say the selling appears irrational and panic-driven, another signal of growing risk aversion. Angelo Mozilo, chief executive of Countrywide Financial, a leading mortgage lender, said on television this week that investors were dumping shares of home loan groups with little regard for a lender's actual fiscal health. "This is now becoming a liquidity crisis," he declared, adding: "It's going to get uglier." The ugliness could spread if lending standards to companies, hedge funds, private equity groups and others come under review.A broad tightening of credit requirements by lenders could have ramifications throughout the markets.(...) As well as affecting US mortgage borrowers, a credit crunch could make hedge funds that use large amounts of borrowed money cut their debt, perhaps selling assets en masse in order to do so. If that led prices to fall, the effect could feed on itself as others scrambled to limit losses. Companies, particularly weak ones, could find it hard to refinance existing debt - potentially leading to a sharply higher incidence of failure, which would further rock credit markets. The worry is that such a wave of "deleveraging" could swell, with few investors both willing and able to start buying and halt the decline in asset prices. "There is an elevated risk of a financial market crisis during the next two months," says T.J. Marta, fixed-income strategist at RBC Capital Markets. "There is a concern that as liquidity tightens, the wheels could fall off." Signs exist that investors have adjusted leverage levels in recent weeks. The yen is tending to strengthen whenever other markets show weakness, an indication that "carry trade" investors - who borrow in yen at low interest rates to finance purchases elsewhere - are at best nervous about their exposure. Steven Wieting, economist at Citigroup, points out that banks have tightened lending standards, at least for mortgages, according to the latest quarterly survey by the Federal Reserve. But he notes that the shift followed a period of easy loan availability, which continued even after mortgage delinquencies began to rise. There seem few signs of investors leaving the debt markets. The huge quantities of capital looking for a home, which have powered the ability of private equity to announce ever larger leveraged buy-outs, have not dried up. Still, analysts worry that the subprime meltdown could be the catalyst that brings the era of easy access to cheap debt to a close.(...) One area where the impact of the subprime mortgage shake-out is already clear is the equity market. Each day on Wall Street seems to bring fresh news of specialist lenders collapsing and fears about possible problems elsewhere, such as at the investment banks that have big subprime holdings. The result is dizzying volatility. Financial stocks have been down since worries over the subprime sector began in earnest in mid-February. The big equity sell-off of February 27, though in part the result of concerns about a possible economic slowdown in China, also demonstrated subprime anxieties in the US. The financial sector took among the biggest tumbles that day, with some banks down by as much as 8 per cent. The power of fear has remained visible this week. Goldman Sachs shares failed to budge even after the bank reported another quarter of stunning earnings on Tuesday - and Goldman does not even have much of a subprime business. Lehman Brothers, which does, saw its shares initially plunge 5 per cent when it reported record results on Wednesday but suggested that it was seeing some impact from problems in the subprime market.(...) "The current battle involving Wall Street firms' subprime exposure and investor perception of contagion risk rages on without any end in sight," says Michael Hecht, a Bank of America analyst. "This is occurring in spite of positive commentary from both Lehman and Goldman Sachs that the sky is not falling." One fear surrounding the investment banks is that while subprime might not be that big a problem on its own, a flight from risk could mean that other profitable Wall Street businesses - such as the packaging of prime mortgages, credit card loans, student loans and other liabilities into securities - would dry up. David Viniar, Goldman's chief financial officer, says such securitisations have been a key part of Wall Street's profit growth. But he adds that he does not think the current subprime problems will derail that growth. "The concept of securitisation, which I think of as the ability to [divide] up credit risk so you can put it in the hands of people who want it as opposed to people taking parts of risk they don't want, has been an important development over the last several years," he says. "It has been good for all of the capital markets - and I still think it will be an important financial tool that will be used, although I think the subprime market will be smaller." The wild ride played out in the larger market as well on Wednesday, as the two main schools of thought (subprime is a disaster versus subprime is no big deal) fought it out, leading to big swings in the main indices. One of the biggest fears among market watchers now is that the worriers will win, whether based on fact or fear, and push stock prices beneath levels that have held even in the face of recent heavy selling pressure. For the Dow Jones industrial average the recent bottom being watched by the market is 12,050, which was hit on March 5. If that level is breached, the theory goes, the rout could quickly turn vicious, with selling begetting more selling and reason going by the wayside. READ IT ALL